Closing Costs in Fort Myers, FL: What Buyers and Sellers Need to Know
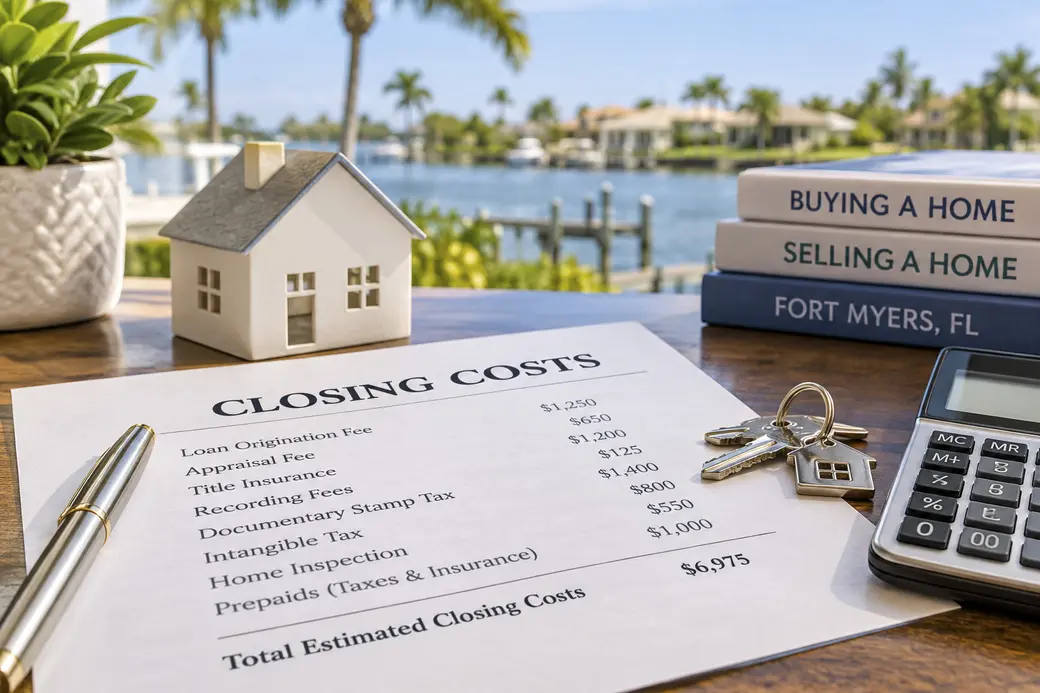
Buying or selling a home in Fort Myers, Florida, involves more than agreeing on a purchase price. There are additional expenses called closing costs, and understanding what they include, who pays them, and how much to budget can help prevent expensive surprises.
As a Fort Myers Realtor and Southwest Florida resident since 1994, I've helped buyers and sellers navigate real estate transactions throughout Lee County, including Fort Myers, Cape Coral, Estero, Bonita Springs, and surrounding communities.
One question I frequently hear is, "Who pays closing costs in Florida, the buyer or the seller?"
The answer depends on the purchase contract. While Lee County has customary practices regarding certain expenses, many closing costs are negotiable.
Here's what buyers and sellers should know before closing on a home in Southwest Florida.
What Are Closing Costs in Florida?
Closing costs are the fees, taxes, and expenses associated with completing a real estate transaction. They're separate from the purchase price and can add thousands of dollars to the amount a buyer needs at closing or reduce the proceeds a seller receives.
Common closing expenses include:
-
Title insurance and title searches
-
Mortgage lender and loan processing fees
-
Appraisal and inspection fees
-
Florida documentary stamp taxes
-
Florida nonrecurring intangible taxes
-
Government recording fees
-
Property tax prorations
-
Homeowners and flood insurance premiums
-
HOA or condominium-related charges
-
Settlement and closing services
Not every transaction includes all these expenses. A cash purchase, for example, generally has fewer closing costs than a financed purchase because there are no mortgage-related charges.
Who Pays Closing Costs in Fort Myers, Florida?
Both buyers and sellers typically have expenses at closing. In Lee County, certain costs are customarily paid by the seller, while others are generally the buyer's responsibility.
However, the signed purchase contract determines who pays which expenses, and many of these responsibilities can be negotiated.
Closing Costs Typically Paid by Buyers
When purchasing a home in Fort Myers with mortgage financing, buyers can generally expect expenses such as:
-
Mortgage origination and underwriting fees
-
Appraisal and credit report fees
-
Home inspections and specialized inspections
-
Survey costs, when applicable
-
Lender's title insurance policy and endorsements
-
Documentary stamp taxes on the mortgage
-
Nonrecurring intangible tax on the mortgage
-
Mortgage and deed recording fees
-
Prepaid homeowners and flood insurance
-
Initial property tax and insurance escrow deposits
-
Applicable HOA or condominium application and transfer fees
Some expenses, such as inspections, may be paid before closing rather than appearing as an amount due on closing day.
Closing Costs Typically Paid by Sellers
In a customary Lee County residential real estate transaction, sellers generally pay expenses such as:
-
Documentary stamp taxes on the deed
-
Owner's title insurance policy and associated charges
-
Applicable title search and closing charges
-
Property taxes prorated through the agreed-upon date
-
Outstanding mortgage balances and liens
-
Mortgage satisfaction and related expenses
-
Negotiated real estate brokerage compensation
-
Certain association estoppel or other charges, depending on the contract
-
Any agreed-upon seller concessions
Knowing these expenses before listing your home is important because the sale price isn't the amount you'll receive at closing.
Florida Documentary Stamp Taxes: What Buyers and Sellers Pay
Florida imposes documentary stamp taxes on certain documents involved in real estate transactions.
One important distinction is that sellers customarily pay documentary stamp taxes on the deed, while buyers obtaining mortgage financing generally pay documentary stamp taxes on their mortgage.
These are two different expenses with different tax rates.
Documentary Stamp Tax on the Deed: Typically a Seller Expense
In Lee County, documentary stamp tax on the deed is generally calculated at $0.70 per $100 of taxable consideration, or $7 per $1,000.
For example, if a home sells for $400,000, the documentary stamp tax on the deed would generally be $2,800.
| Home Sale Price | Documentary Stamp Tax on Deed |
|---|---|
| $250,000 | $1,750 |
| $300,000 | $2,100 |
| $350,000 | $2,450 |
| $400,000 | $2,800 |
| $500,000 | $3,500 |
| $600,000 | $4,200 |
These examples assume the sale price equals the taxable consideration. The tax is calculated on each $100 or portion thereof.
In most residential transactions in Fort Myers and Lee County, the seller pays this tax, although the purchase contract can provide otherwise.
Documentary Stamp Tax on the Mortgage: Typically a Buyer Expense
When purchasing a home with a mortgage, buyers generally pay a separate documentary stamp tax based on the amount financed.
Florida's documentary stamp tax on recorded mortgages is $0.35 per $100 of the mortgage amount, or portion thereof.
For example, suppose you're purchasing a $400,000 home and financing $320,000.
Your mortgage documentary stamp tax would generally be:
$320,000 ÷ $100 × $0.35 = $1,120
This tax is calculated on the mortgage amount, not the purchase price.
Florida Nonrecurring Intangible Tax: Another Buyer Expense
In addition to mortgage documentary stamp taxes, Florida imposes a nonrecurring intangible tax on certain obligations secured by Florida real estate.
The tax is $0.20 per $100 of the mortgage amount, equivalent to 0.2%.
Using the same $320,000 mortgage:
$320,000 × 0.002 = $640
Although the lender is legally responsible for this tax, the expense is commonly passed along to the buyer as part of the loan's closing costs.
How Much Are Mortgage Documentary Stamp and Intangible Taxes Combined?
Here's what buyers can generally expect to pay at different mortgage amounts:
| Mortgage Amount | Doc Stamps | Intangible Tax | Combined |
|---|---|---|---|
| $200,000 | $700 | $400 | $1,100 |
| $250,000 | $875 | $500 | $1,375 |
| $300,000 | $1,050 | $600 | $1,650 |
| $350,000 | $1,225 | $700 | $1,925 |
| $400,000 | $1,400 | $800 | $2,200 |
These examples assume standard taxable mortgages. Certain transactions and loan programs may qualify for exemptions, and exact calculations depend on applicable Florida tax rules.
My advice to buyers: Make sure both taxes are included in your lender's closing-cost estimate. On a $320,000 mortgage, these two expenses alone would generally total $1,760.
Who Chooses the Closing Agent in Lee County, Florida?
This is one area where local real estate customs make a difference.
In Lee County, it is customary for the seller to designate the closing agent and pay for the owner's title insurance policy and associated charges.
The Florida Realtors/Florida Bar residential purchase contracts provide different options for allocating these responsibilities, so buyers and sellers can negotiate an arrangement that differs from local custom.
What Does a Closing Agent Do?
A closing agent is typically a title company or real estate attorney responsible for coordinating the closing process.
The closing agent's responsibilities generally include:
-
Conducting or coordinating the title search
-
Identifying outstanding liens and title issues
-
Obtaining mortgage payoff information
-
Preparing settlement documents
-
Coordinating the receipt and disbursement of funds
-
Recording the deed and mortgage documents
-
Coordinating the issuance of title insurance policies
The closing agent helps ensure the financial and title-related requirements are addressed so ownership can be transferred according to the contract.
What Is Owner's Title Insurance, and Who Pays for It?
An owner's title insurance policy protects the buyer's ownership interest against certain covered title problems that existed before the property was purchased.
These may include:
-
Undiscovered liens
-
Errors in public records
-
Certain forged or fraudulent documents
-
Unknown ownership claims
-
Other covered defects in the property's title
For example, suppose you purchase a home and later discover a covered ownership claim involving a previous transaction. An owner's title insurance policy may provide protection against covered financial losses and legal expenses, subject to the policy's terms.
Unlike homeowners insurance, which generally protects against covered future damage to a home, title insurance addresses covered problems involving the property's ownership history.
Owner's title insurance is generally purchased through a one-time premium at closing, rather than an annual payment.
What Are Owner's Policy and Charges?
In the Florida Realtors/Florida Bar residential contract, the term "Owner's Policy and Charges" refers to the owner's title insurance premium, title search, and specified closing services.
Under the customary seller-designated closing agent arrangement in Lee County, the seller pays these expenses.
This means the seller generally selects the closing agent and pays for the owner's title insurance policy and associated charges identified in the contract.
However, buyers and sellers can negotiate a different arrangement, and the selected contract provisions control.
What Is Lender's Title Insurance, and Who Pays for It?
When a buyer finances a home, the mortgage lender generally requires a lender's title insurance policy.
This policy protects the lender's financial interest in the property against certain covered title issues.
Lender's title insurance protects the lender, not the homeowner.
In a customary Lee County transaction where the seller pays for the owner's title policy, the buyer generally pays the premium for the lender's title insurance policy and any required endorsements.
What Are Title Insurance Endorsements?
Endorsements are additions to a title insurance policy that provide specific coverage or modify certain policy provisions.
A lender may require endorsements based on the property, loan type, or underwriting requirements.
These can create additional expenses for the buyer.
The buyer may also be responsible for closing services related specifically to the lender's policy and loan closing, depending on the contract.
Who Pays Title Insurance and Closing Agent Charges in Lee County?
| Expense | Customary Responsibility |
|---|---|
| Selection of closing agent | Seller |
| Owner's title insurance policy | Seller |
| Owner's policy title search and associated charges | Seller |
| Lender's title insurance policy | Buyer |
| Lender's title policy endorsements | Buyer |
| Loan-related closing charges | Buyer, as provided in the contract |
Important: These are customary practices, not mandatory rules. The contract determines which party pays each expense.
How Much Are Closing Costs for Buyers in Fort Myers?
As a general budgeting guideline, buyers purchasing a home in Fort Myers with financing may want to allow approximately 2% to 5% of the purchase price for closing costs and prepaid expenses, excluding the down payment.
Actual costs vary considerably depending on the lender, loan program, insurance premiums, property type, and negotiated terms.
| Home Price | Estimated Buyer Closing Costs |
|---|---|
| $250,000 | $5,000–$12,500 |
| $300,000 | $6,000–$15,000 |
| $400,000 | $8,000–$20,000 |
| $500,000 | $10,000–$25,000 |
| $600,000 | $12,000–$30,000 |
These estimates are for planning purposes and aren't guaranteed ranges.
Example: Buying a $400,000 Home in Fort Myers
Suppose you're purchasing a $400,000 home with a 20% down payment.
-
Purchase price: $400,000
-
Down payment: $80,000
-
Mortgage amount: $320,000
-
Mortgage documentary stamp tax: $1,120
-
Nonrecurring intangible tax: $640
Your mortgage-related state taxes would generally total $1,760.
You would also need to budget for applicable lender fees, appraisal, inspections, insurance, recording fees, title-related expenses, and prepaid costs.
Your down payment is separate from these expenses.
The amount you actually need at closing will depend on the final settlement figures and any deposits or credits already applied.
If you're planning a move to Southwest Florida, my complete guide to buying a home and living in Fort Myers covers additional housing expenses, neighborhoods, and considerations that can affect your overall budget.
How Much Are Closing Costs for Sellers in Fort Myers?
Seller closing costs depend on the sale price, contract terms, mortgage payoff, title expenses, prorations, and negotiated compensation.
For example, a seller closing on a $400,000 home would generally pay $2,800 in documentary stamp taxes on the deed.
Other potential expenses include:
-
Owner's title insurance premium
-
Title search and applicable closing services
-
Prorated property taxes
-
Association-related charges
-
Negotiated real estate compensation
-
Seller concessions, if applicable
-
Outstanding mortgages or liens
Mortgage payoff balances aren't technically closing service fees, but they reduce the amount of money the seller receives.
Why Sellers Should Request a Net Sheet
Before listing a home, I recommend reviewing a seller's estimated net sheet.
This document provides an estimate of the money you may receive after deducting expected selling expenses and outstanding obligations.
It can also help you evaluate offers that include different purchase prices, closing dates, or requests for seller concessions.
A higher offer isn't always the offer that produces the highest net proceeds.
For a more detailed look at the selling process, read my guide to selling a house in Fort Myers, Florida, which covers preparing your property, pricing strategies, evaluating offers, and navigating the transaction.
You can also review my article on typical seller closing costs in Lee County, Florida for additional information about estimating your proceeds.
Are Closing Costs Lower for Cash Buyers in Florida?
Generally, yes.
Cash buyers avoid many mortgage-related expenses, including:
-
Loan origination and underwriting fees
-
Lender-required appraisals
-
Mortgage documentary stamp taxes
-
Mortgage-related intangible taxes
-
Lender's title insurance
However, cash buyers still have closing expenses, which may include title-related charges, recording fees, inspections, surveys, association fees, and prorations.
Even when purchasing with cash, I recommend obtaining appropriate inspections and considering an owner's title insurance policy.
Paying cash doesn't eliminate the possibility of property defects or ownership-related issues.
If you're considering a seasonal residence or second home, my article on buying a vacation home in Southwest Florida discusses additional costs and responsibilities to consider before purchasing.
Are Closing Costs Different When Buying a Condo in Fort Myers?
They can be.
Condominium purchases in Fort Myers, Cape Coral, Estero, and Bonita Springs may involve additional association-related expenses.
Depending on the condominium community, buyers and sellers may encounter:
-
Association application fees
-
Transfer fees
-
Estoppel certificate fees
-
Capital contributions
-
Prorated condominium dues
-
Special assessment adjustments
These costs vary by association and contract.
Condominium buyers should also review the association's financial condition, insurance coverage, reserve funding, and any existing or anticipated special assessments.
A condominium with a lower purchase price isn't necessarily less expensive to own once monthly fees, insurance, and potential assessments are considered.
Do CDD Fees Affect Closing Costs in Southwest Florida?
Some Southwest Florida communities have Community Development Districts, commonly called CDDs.
A CDD is a special-purpose local government that helps finance, operate, or maintain certain community infrastructure and improvements.
CDD assessments are included on the annual property tax bill.
When purchasing a home in a CDD community, applicable assessments may affect closing prorations and the buyer's future annual expenses.
It's important to understand that CDD fees and HOA fees are not the same thing.
A community may have both.
Before purchasing in a neighborhood with a CDD, buyers should understand the annual assessment and how it affects their overall housing expenses.
For a more detailed explanation, read my article, What Are CDD Fees in Florida? A Simple Guide for Home Buyers.
How Are Property Taxes Prorated at Closing in Florida?
Florida property taxes are generally paid in arrears.
This means the annual property tax bill covers the year that is ending, rather than the upcoming year.
Because of this, sellers typically provide buyers with a credit for the portion of the year's property taxes attributable to the seller's ownership period.
The exact proration depends on the closing date, available tax information, and terms of the contract.
Why the Seller's Current Property Taxes Can Be Misleading
This is especially important for buyers relocating to Fort Myers or purchasing their first Florida home.
The property taxes currently paid by the seller may be significantly different from what the buyer will pay after purchasing the property.
Florida's homestead exemption and Save Our Homes assessment limitation can reduce the taxable value of a longtime owner's primary residence.
When ownership changes, the property's assessed value may be reset under Florida law, potentially resulting in higher property taxes for the new owner.
My advice: Don't rely on the seller's current property tax bill when calculating your future housing expenses. Review an estimate based on the property's anticipated value after the sale and your own exemption eligibility.
Does Flood Insurance Affect Closing Costs in Fort Myers?
It can.
Fort Myers and surrounding Southwest Florida communities include homes located in different FEMA flood zones.
Depending on the property's flood zone and financing, a lender may require flood insurance.
When flood insurance is required, the buyer may need to pay the initial premium before or at closing.
Even when a lender doesn't require flood insurance, buyers should consider obtaining coverage because flooding can occur outside designated high-risk areas.
Homeowners insurance and flood insurance are separate policies.
These premiums can have a significant impact on the total cash needed to close and the ongoing cost of owning a home in Southwest Florida.
For more information about local flood designations, read my article on flood zones in Fort Myers, Florida.
Can Buyers Ask Sellers to Pay Closing Costs in Florida?
Yes. Buyers can negotiate for sellers to contribute toward allowable closing expenses.
These contributions are commonly called seller concessions.
For example, a buyer purchasing a $350,000 home might request that the seller contribute $7,000 toward closing costs.
Whether the seller agrees depends on the offer, property, market conditions, and other negotiated terms.
Mortgage programs also have different rules regarding allowable seller contributions.
Conventional, FHA, VA, and other loan programs may limit the amount or types of costs that can be covered.
Buyers should discuss these options with their lender before submitting an offer.
Can Closing Costs Change Before Closing?
Yes. Closing-cost estimates can change as the transaction progresses.
For most mortgages subject to federal disclosure requirements, buyers receive a Loan Estimate early in the financing process and a Closing Disclosure at least three business days before consummation.
The Closing Disclosure details the final loan terms, closing expenses, and amount needed to complete the transaction.
Changes may result from:
-
Updated property tax prorations
-
Final insurance premiums
-
HOA or condominium adjustments
-
Prepaid interest calculations
-
Permitted lender or third-party fee adjustments
-
Negotiated seller credits
Certain lender charges are subject to federal limits on how much they can increase.
Buyers should carefully compare their Closing Disclosure with their original Loan Estimate and ask questions about any unexpected differences.
Cash buyers generally receive a settlement statement rather than a mortgage Closing Disclosure.
What Should Buyers and Sellers Review Before Closing Day?
Before signing the final documents, both parties should carefully review their settlement figures.
Buyers should confirm:
-
Purchase price and loan amount
-
Down payment and total cash needed
-
Mortgage documentary stamp and intangible taxes
-
Lender fees and title insurance charges
-
Insurance premiums and escrow deposits
-
Property tax and association prorations
-
Seller concessions and credits
-
Any applicable HOA or condominium charges
Sellers should confirm:
-
Final sale price
-
Mortgage payoff amounts
-
Documentary stamp taxes on the deed
-
Owner's title insurance and closing charges
-
Property tax prorations
-
Association fees and assessments
-
Negotiated brokerage compensation
-
Seller concessions
-
Estimated net proceeds
It's much easier to resolve a question about closing expenses before everyone arrives at the closing table.
Frequently Asked Questions About Closing Costs in Fort Myers, Florida
Who pays closing costs in Fort Myers, Florida?
Both buyers and sellers generally pay closing costs. Buyers commonly pay mortgage-related fees, inspections, recording charges, and lender's title insurance. Sellers customarily pay documentary stamp taxes on the deed, owner's title insurance, and certain title-related charges in Lee County. The purchase contract determines the final allocation.
Who chooses the title company in Lee County, Florida?
In Lee County, it is customary for the seller to designate the closing agent and pay for the owner's title insurance policy and associated charges. However, this is negotiable, and the signed purchase contract determines which party selects the closing agent.
Who pays for the lender's title insurance policy in Florida?
Buyers obtaining mortgage financing generally pay for the lender's title insurance policy and any required endorsements. The lender's policy protects the mortgage lender's financial interest in the property rather than the homeowner.
How much are documentary stamp taxes on a Florida mortgage?
Florida's documentary stamp tax on recorded mortgages is $0.35 per $100 of the mortgage amount, or portion thereof. On a $300,000 mortgage, the tax would generally be $1,050.
How much is Florida's intangible tax on a mortgage?
Florida's nonrecurring intangible tax is generally 0.2% of the mortgage amount secured by Florida real estate. On a $300,000 mortgage, the tax would typically be $600.
How much are closing costs on a $400,000 home in Fort Myers?
A financed buyer purchasing a $400,000 home might budget approximately $8,000 to $20,000 for closing costs and prepaid expenses, excluding the down payment. Actual costs depend on financing, insurance, property type, and contract terms.
Does the seller pay documentary stamp taxes in Florida?
In most Lee County residential transactions, the seller pays the documentary stamp tax on the deed, generally calculated at $0.70 per $100 of taxable consideration. Buyers with mortgage financing typically pay the separate documentary stamp tax associated with their mortgage.
Can closing costs be negotiated in Florida?
Yes. Many closing expenses can be negotiated, including responsibility for certain title charges and seller contributions toward the buyer's allowable closing costs. Government tax rates are established by law, although the contract can address which party pays certain taxes.
Are closing costs different for new construction homes in Fort Myers?
They can be. New construction purchases may involve builder-specific charges, community fees, CDD assessments, and different title or closing arrangements. Some builders offer closing-cost incentives when buyers use preferred lenders or title companies. Buyers should compare the complete transaction costs before deciding whether an incentive is beneficial.
Do first-time home buyers pay closing costs in Florida?
Yes. First-time buyers generally pay applicable closing costs, just like other purchasers. However, some may qualify for state, local, or lender assistance programs that help with down payments or allowable closing expenses.
For more information about one potential assistance option, read my article about the Florida Hometown Heroes Program for Fort Myers home buyers. Program availability, funding, and eligibility requirements can change.
Understanding Closing Costs Before Buying or Selling in Southwest Florida
Whether you're purchasing your first home, relocating to Fort Myers, buying a seasonal property, or selling a home you've owned for years, understanding closing costs is an important part of making informed financial decisions.
While online closing-cost calculators can provide a starting point, they don't always account for details specific to Southwest Florida, such as Lee County title insurance customs, Florida mortgage taxes, property tax reassessments, flood insurance, condominium fees, and CDD assessments.
And because many expenses are negotiable, understanding your options before signing a purchase contract can make a meaningful difference.
Thinking about buying or selling a home in Fort Myers, Cape Coral, Estero, Bonita Springs, or the surrounding Southwest Florida area?
I'm happy to help you understand what expenses to expect, which costs may be negotiable, and how the financial details of a transaction can affect your bottom line.
My goal is to help you make informed decisions, avoid unnecessary surprises, and feel confident throughout the buying or selling process.
About the Author: Billee Silva, PA
Billee Silva, PA, is an award-winning, top-producing Fort Myers Realtor with Century 21 AllPoints Realty, serving buyers and sellers throughout Fort Myers, Cape Coral, Estero, Bonita Springs, and surrounding Southwest Florida communities.
A Southwest Florida resident since 1994, Billee combines extensive local knowledge with a background in education, communications, and marketing. She holds the Accredited Buyer's Representative (ABR), Seller Representative Specialist (SRS), and Commitment to Excellence (C2EX) designations.
Recognized for her real estate performance and dedication to client service, Billee helps buyers and sellers navigate the details of real estate transactions, from pricing and property searches to inspections, negotiations, and closing.
Billee Silva, PA — Doing Everything but the Packing!
Visit www.sw-floridarealtor.com to learn more about buying or selling real estate in Southwest Florida.
Disclaimer: Closing costs, tax calculations, insurance requirements, and customary practices can vary by transaction. This article provides general educational information and should not replace estimates from your lender, closing agent, tax professional, or legal adviser.
Categories
- All Blogs 406
- 55+ Communities 12
- Boating Communities 13
- First Time Home Buyer 147
- Flood Insurance 3
- Florida Lifestyle 69
- Foreclosures 2
- Fort Myers Market Update 5
- Fun Things to do in Lee County, Florida 37
- Golf Communities 23
- Home Buyer Tips 168
- Home Seller Tips 124
- Homeowner Tips 64
- Mortgage Tips 44
- Neighborhoods 75
- Schools 4
- Title & Escrow 4
- Title Insurance 5
Recent Posts
GET MORE INFORMATION
Billee Silva, PA, ABR SRS
Licensed Realtor License ID: P3275278
Licensed Realtor License ID: P3275278